To calculate your net worth, add up everything you own, add up everything you owe, and subtract the second number from the first. The formula is assets minus liabilities, and AARP’s calculator page describes it the same way: what you own minus what you owe. The math takes seconds. The real work is gathering honest numbers, and that usually takes an hour or less.
Below we walk through the full process, show a worked example with real arithmetic, and explain what to do with the number once you have it.
TL;DR
- Net worth = total assets − total liabilities. Value everything at what it is worth today, not what you paid.
- Retirement accounts and home equity count. Future income, Social Security and leased cars generally do not.
- A negative result is common early in a career, especially with student loans. It describes a starting point, not a verdict.
- Net worth is a snapshot, so recalculate once or twice a year and watch the direction of the trend.
- Income and net worth are different measures: one is what you earn, the other is what you keep and build.
Table of Contents
- What net worth actually measures
- The net worth formula, step by step
- What counts as an asset
- What counts as a liability
- A worked example
- Should you include your home?
- How to read your result
- Net worth vs. income
- Our perspective
- Tools that do the adding for you
- Make the number work for you
- Where Win Personal Finance fits in
- FAQ
- Sources
What net worth actually measures
Net worth is the value of your assets minus the total of your liabilities. Investor.gov, the SEC’s investor education site, calls this list a net worth statement: on one side what you own, on the other what you owe.
Two plain definitions help:
- Assets are things you own that have monetary value: cash, investments, retirement accounts, property, vehicles.
- Liabilities are money you owe: mortgages, auto loans, student loans, credit card balances, medical debt, personal loans.
If you own more than you owe, your net worth is positive. If you owe more than you own, it is negative. AARP’s explanation states both cases directly.
Because net worth is a static snapshot, it does not tell you how much cash is coming in each month. That distinction matters, and we come back to it below.
The net worth formula, step by step
You can do this on paper, in a spreadsheet or in a free app. The steps are the same.
- Pick a date. Use today or the last day of the month. All balances should come from that same day or close to it.
- List your assets. Pull current balances from every account you have.
- Value the big items realistically. Use a market estimate for your home and a used-car price guide for your vehicle.
- List your liabilities. Use the current payoff balance, not the original loan amount.
- Add each column. You now have total assets and total liabilities.
- Subtract. Total assets minus total liabilities is your net worth.
Write the date on your sheet. When you repeat the exercise next year, the date makes comparison easy.
What counts as an asset
Start with the accounts you can log into, then move to the things you own physically.
Cash and cash equivalents
Checking, savings, money market accounts, certificates of deposit and any cash you keep at home. Use the balance as of your chosen date.
Investments and retirement accounts
Brokerage accounts, IRAs, Roth IRAs, 401(k)s, 403(b)s, HSAs you invest, and similar accounts. Yes, a 401(k) counts. Value it at its current account balance. If you want to understand how much you can add to it each year, our guide to 401(k) contribution limits covers the current rules, and our comparison of Roth vs. traditional IRAs can help you decide where new savings should go.
One optional refinement: pre-tax accounts like a traditional 401(k) will be taxed when you withdraw. Some people subtract an estimated tax cost for a more conservative figure. Most standard calculators use the plain balance, and for tracking your trend either approach works as long as you stay consistent.
Real estate
Your home counts at its current market value, and your mortgage goes on the liability side. Put another way, you are counting home equity: market value minus the mortgage balance. The U.S. Census Bureau treats home equity as a core part of household net worth, and it found that rising home equity was the main reason median household net worth grew between 2019 and 2022.
Be conservative. A recent comparable sale in your neighborhood is more reliable than an optimistic online estimate.
Vehicles and personal property
Cars you own outright or are paying off count at their current resale value. Do the same for boats, motorcycles or a trailer. For household goods, jewelry and electronics, many people include only items they could actually sell for meaningful money, such as an engagement ring or a collectible. Counting the value of every couch inflates the total without helping you.
Business interests and other holdings
If you own part of a business, include a realistic value for your share. Add money owed to you if it is likely to be repaid, and other items such as cryptocurrency at today’s price.
What to leave out
A leased vehicle you do not own, future paychecks, expected inheritances, and Social Security benefits you have not yet received are not assets today. Keep the statement to things you hold now.
What counts as a liability
Use the payoff balance as of your chosen date.
- Mortgage and home equity loans or lines of credit
- Auto loans
- Student loans, federal and private
- Credit card balances (the full statement balance, even if you pay it off each month)
- Personal loans and buy-now-pay-later balances
- Medical debt, back taxes, and money you owe family or friends
One frequent mistake is leaving out smaller debts because they feel temporary. A statement that ignores a $2,700 card balance is not wrong by much, but it is no longer honest, and the purpose of this exercise is honesty. If card debt is a big part of your list, our guide to balance transfers vs. personal loans shows how to pay it down without letting it return.
A worked example
Here is an illustration with made-up numbers for a 29-year-old renter. These are not averages or real data, just arithmetic you can follow.
| Assets | Value |
|---|---|
| Checking account | $3,200 |
| High-yield savings | $8,500 |
| 401(k) | $24,000 |
| Roth IRA | $6,300 |
| Car (current resale value) | $14,000 |
| Total assets | $56,000 |
| Liabilities | Balance |
|---|---|
| Student loans | $31,500 |
| Auto loan | $9,800 |
| Credit card | $2,700 |
| Total liabilities | $44,000 |
Net worth: $56,000 − $44,000 = $12,000.
Notice what drives that number. The retirement accounts are $30,300 of the total, but the person can’t spend them without penalties before retirement age. Meanwhile liquid cash is $11,700, which would cover only part of a few months of expenses. Net worth is positive, yet the cash position is thin. The statement is useful precisely because it shows both facts at once.
A homeowner version
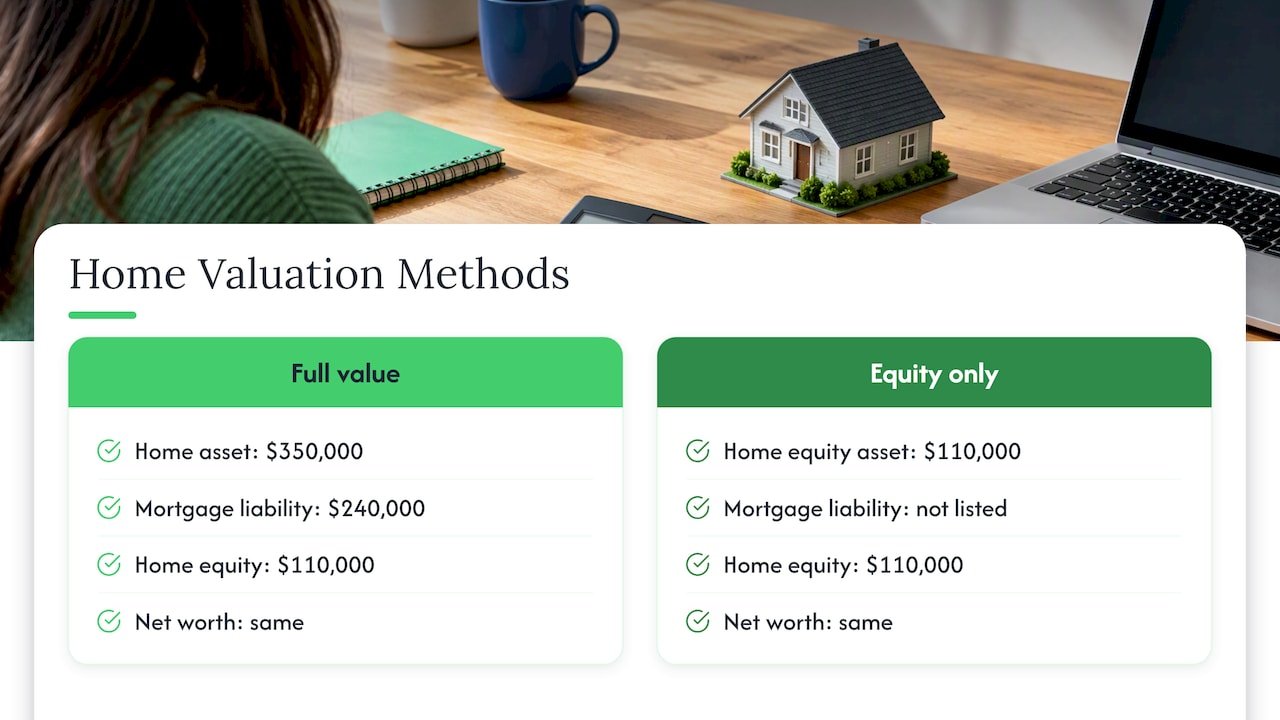
Suppose a household owns a home worth $350,000 with a $240,000 mortgage balance. Home equity is $110,000. Add that to the other assets, and the mortgage is already netted out, so be careful not to subtract the mortgage twice. If you list the full $350,000 as an asset, list the full $240,000 as a liability. If you list only the $110,000 equity, leave the mortgage off the liability side. Both methods give the same net worth.
Should you include your home?
It depends on the question you are asking.
The Federal Reserve’s Survey of Consumer Finances, the standard government measure of household wealth, includes home equity in total net worth. If you want to know your total wealth, include it.
If you want to know whether your savings can generate retirement income, many people also calculate an “investable” net worth that leaves out the primary residence, because you can’t spend your house while you live in it. We suggest calculating both once and tracking the one that matches your goal.
How to read your result
If your number is negative
People are often surprised that net worth can be negative, especially early in a career when student loans or a new mortgage outweigh savings. This is common and says little about your character or future. It is simply a balance sheet where liabilities currently exceed assets. Steadily paying down debt and building assets will move the number. The Federal Reserve’s survey documentation reflects that households carry a wide range of balances, including negative ones.
If your number is positive
Good. Next question: how liquid is it? A large net worth tied up in a house and retirement accounts can leave you cash-constrained when an emergency hits. AARP’s guidance makes the same point: a positive net worth can still leave you cash poor if your assets are illiquid.
How you compare with other households
Comparisons can motivate you or discourage you, so treat them as context only. Census Bureau data from the Survey of Income and Program Participation put median U.S. household net worth at $176,500 in 2022. The Federal Reserve’s survey reports real median net worth rose 37 percent between 2019 and 2022, though that surge came from a unusual stretch of rising home and asset values. Net worth generally rises with age, so a 28-year-old should not measure themselves against a 58-year-old.
As for “wealthy,” there is no universal line. One analysis suggests $3 million places a household in roughly the top 2%, with the top 1% requiring much more. For most readers, the goal is a number that rises, not a number that matches someone else’s.
Net worth vs. income
Income and net worth answer different questions. Income is a flow: what comes in over a period. Net worth is a stock: what you hold at a moment in time. The Federal Reserve’s consumer finance survey tracks both, and the two do not always move together.
A high earner who spends everything can have a low or even negative net worth. A modest earner who saves steadily and lets assets grow can build a large one. Income is the raw material, and savings rate, debt choices and time turn it into wealth. For a view of how cash-flow gaps are mapped in a very different field, see this look at how developers test cash flow before committing funds. The principle carries over: income timing and outflows decide whether you stay solvent, while accumulated assets show where you’ve ended up.
If you want to raise the income side, our guides on side hustle ideas and asking for a raise give you practical places to start.
Our perspective
We talk with a lot of readers who avoid calculating net worth because they fear the answer. We think that is backwards. The number is not a grade. It is a starting line, and you can’t plan a route without knowing where you stand.
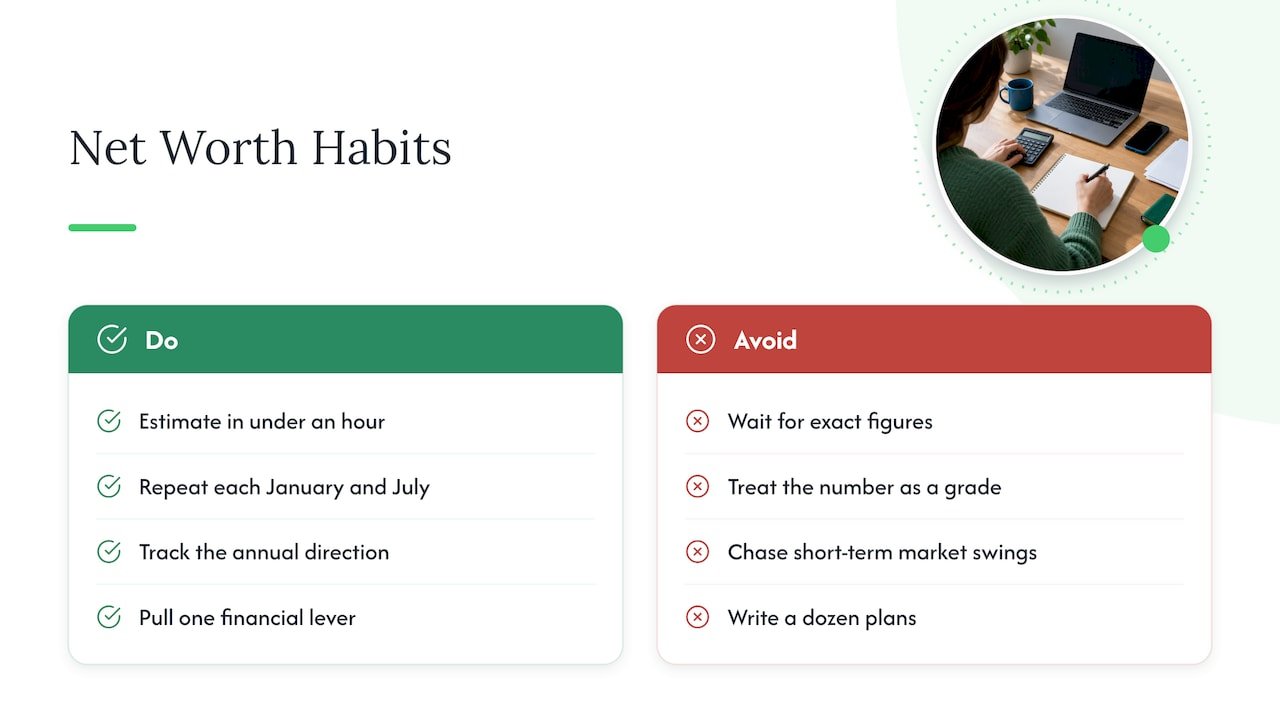
Here is what we recommend. Calculate it once, imperfectly, in under an hour. Do not wait for exact figures: a rough estimate you finish beats a perfect one you never start. Then set a repeat date, such as every January and July, and track only the direction. Short-term swings from the stock market are noise. Annual trends are signal.
Then pick one lever. Maybe it is the highest-interest debt. Maybe it is raising your savings rate by two percentage points. Maybe it is increasing income. A single lever you actually pull will do more for your net worth than a dozen plans on paper. Pair your number with a goal, and the exercise becomes motivating rather than stressful.
— Win Personal Finance
Tools that do the adding for you
A spreadsheet works fine, but you can also use a free calculator or a budgeting app that links to your accounts and updates balances automatically. Linked tools save time, though you should still review them for missed accounts and wrong home or car values. We reviewed options in our list of best free financial wellness tools, including ones that track net worth over time.
If you want a printable option, the U.S. Department of Labor’s personal finance worksheets include forms for listing your financial information.
Make the number work for you
Once you know your net worth, we suggest turning it into a plan:
- Write down your number and the date.
- Set one measurable target for the next 12 months. Our SMART financial goals guide shows how to build a weekly plan around it.
- Build a repeatable system, from budgeting habits to automatic savings. Our budgeting habits article and savings challenge ideas are good starting points.
- Recalculate on your scheduled date and compare.
If you are about to make a big change like moving out, our moving out budget guide helps you see how the first-year costs will affect your balance sheet.
Where Win Personal Finance fits in
Calculating your net worth is step one. Step two is deciding what to change. At Win Personal Finance we publish step-by-step guides on budgeting, debt reduction, saving and increasing income, written in plain language for beginners. If you want a full roadmap after you finish your statement, start with our financial management plan.
We provide educational content, not licensed financial planning. If your situation involves complex taxes, an inheritance, a business sale or large estate questions, a fee-only certified financial planner or a CPA is the right person to see.
FAQ
Does a 401(k) count toward net worth?
Yes. A 401(k) is a financial asset, so you include its current account balance. If you want a more conservative number, you can reduce it by the estimated tax you would owe on withdrawal, but be consistent from year to year.
Do you count home equity in net worth?
Yes. Home equity is the market value of your home minus your remaining mortgage, and government measures such as the Census Bureau’s include it in household net worth. If you want to gauge retirement readiness, you may also calculate a second figure that excludes your primary residence.
How often should you calculate your net worth?
Once or twice a year is enough for most people. AARP-style guidance points toward tracking long-term trends, because monthly market swings can cause needless worry. Monthly checks make sense only if you are actively paying down debt and want to see progress.
Is a negative net worth bad?
Not necessarily. Many people start their careers with student loans and few assets, so liabilities exceed assets for a while. What matters is the direction: as you pay down debt and build savings, the number rises.
Is $3 million considered wealthy?
There is no official definition. One analysis of U.S. percentiles places $3 million in about the top 2% of households, though what feels wealthy depends on your age, location and goals.
Sources
- AARP: Net Worth Calculator
- Investor.gov: Figure Out Your Finances
- U.S. Census Bureau: Median Home Equity Rose From 2019 to 2022
- Federal Reserve: Survey of Consumer Finances 2022 bulletin
- Federal Reserve: 2022 SCF codebook
- Gerald: U.S. Net Worth Percentiles