Term life insurance gives you temporary, lower-cost coverage with no cash value, while whole life gives you permanent protection at a higher price that builds cash value over time. If you have temporary obligations like a mortgage or young kids to raise, term usually fits better and frees up money for other goals. If you want lifetime coverage, estate planning tools, or a forced-savings feature attached to your policy, whole life is worth a closer look. We’ll walk through costs, cash value mechanics, policy features, and a simple checklist to help you decide.
TL;DR:
- Whole life premiums can cost five to fifteen times more than term for comparable coverage, and dividends on participating policies are never guaranteed.
- At term expiration, annual renewals keep coverage but sharply raise premiums; a conversion rider can preserve access to permanent coverage without new medical underwriting.
- Cash value typically builds slowly in a policy’s first several years; surrender charges reduce early cancellation proceeds, and unpaid loans reduce beneficiaries’ death benefit.
- Buying term and investing the difference works only if you invest the savings consistently; market returns are uncertain, while whole life guarantees minimum cash value.
Table of Contents
- Key differences between term and whole life insurance
- What drives the cost gap between term and whole life
- How cash value builds and how you can use it
- How long coverage lasts and what renewal really means
- Which policy fits your situation
- The “buy term and invest the difference” approach
- How to choose between term and whole life
- Our take on making this decision without the pressure
- Where to go next for budgeting and coverage planning
- FAQ
- Sources
Key differences between term and whole life insurance
The two policy types solve different problems, and the gap between them shows up in five areas: how long coverage lasts, what you pay, whether cash value builds, what’s guaranteed, and how complicated the paperwork gets.
Term life insurance covers you for a set period, typically 10, 20, or 30 years. If you die during that window, your beneficiaries receive the death benefit tax-free. If you outlive the term, coverage simply ends unless you renew or convert it. Whole life insurance, by contrast, lasts your entire life as long as you keep paying premiums, and it’s built to stay in force rather than expire on a schedule, according to AARP’s comparison of the two policy types.
Cost is where the two diverge sharply. Term premiums start low because the insurer is only on the hook for a limited window and the policy carries no savings component. Whole life premiums run much higher because part of every payment funds a cash value account on top of the death benefit, a distinction Forbes Advisor lays out clearly when comparing the two.
Cash value is the other defining split. Term policies never build it. Whole life policies do, and that cash value grows on a tax-deferred basis that you can tap while you’re still alive, whether through a loan or a withdrawal.
Here’s how the core features stack up:
- Coverage length: Term ends at a set date; whole life continues for life with premiums paid.
- Premium cost: Term starts cheap; whole life costs substantially more for the same death benefit.
- Cash value: Absent in term; present and growing in whole life.
- Guarantees: Whole life often includes guaranteed minimum cash value and, in participating policies, the potential for dividends.
- Complexity: Term is simple to quote and compare; whole life requires reading an illustration and understanding surrender charges before you commit.
The NAIC’s Life Insurance Buyer’s Guide frames this as a budget and needs question rather than a right-or-wrong one: term is generally the most cost-effective way to get a large death benefit for a defined period, while cash-value policies suit people who want permanent coverage or a savings and estate-planning feature built into their insurance.
What drives the cost gap between term and whole life
Whole life premiums run several times higher than term premiums for the same death benefit because you’re paying for two things at once: lifelong coverage and a savings account the insurer has to fund and manage. Term premiums only cover the mortality risk for a defined window, which keeps the price down.
Whole life can cost five to fifteen times more than term for comparable coverage, according to CNBC Select’s reporting on the two policy types, reflecting the cash-value funding and lifetime guarantee built into permanent coverage.
A handful of factors shape what you’ll actually pay, whichever type you choose:
- Age and health: Younger, healthier applicants lock in lower rates on both term and whole life.
- Sex and tobacco use: Insurers price risk differently by sex and penalize tobacco use heavily.
- Term length: A 30-year term costs more than a 10-year term because the insurer carries the risk longer.
- Riders: Added benefits like disability waivers or accelerated death benefits raise the premium.
- Dividend and crediting practices: For participating whole life policies, the insurer’s dividend history affects projected (not guaranteed) returns.
A few whole life variants change the cost picture further. Limited-pay whole life lets you finish paying premiums in 10 or 20 years while coverage continues for life, which raises the annual premium but shortens the payment period. Single-premium whole life trades one large upfront payment for guaranteed lifetime coverage. Convertibility riders on term policies let you switch to permanent coverage later without new medical underwriting, which matters if your health changes before you’re ready to commit to whole life.
How cash value builds and how you can use it
Part of every whole life premium goes toward your death benefit and part funds a cash value account that grows on a tax-deferred basis. Over time, you can borrow against that cash value or withdraw from it, giving you a living benefit that term insurance never offers, as AARP notes in its breakdown of the two products.
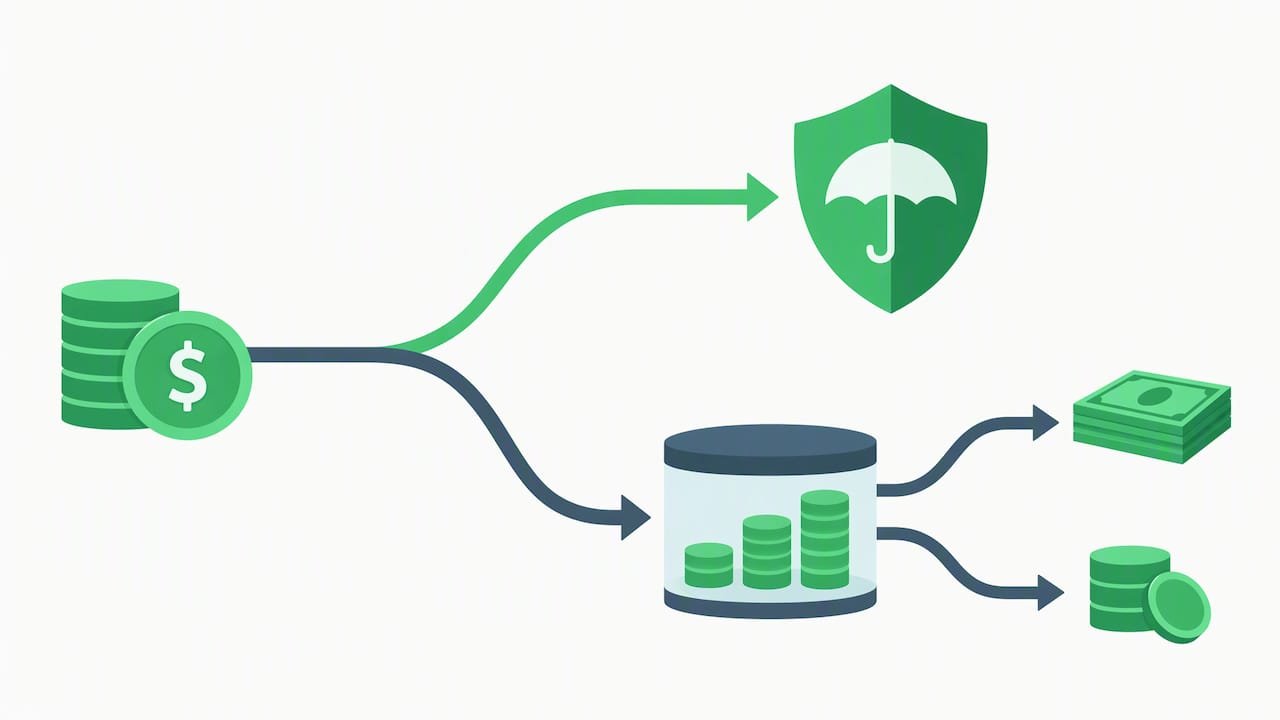
Not all whole life policies work the same way. Participating policies, usually issued by mutual insurers, can pay dividends based on company performance, but those dividends are never guaranteed. Nonparticipating policies skip dividends entirely and focus on guaranteed cash value growth instead.
A few practical constraints matter before you count on cash value as a resource:
- Surrender charges: Canceling a policy in its early years often triggers a charge that reduces what you receive.
- Limited early access: Cash value typically builds slowly in the first several years, so don’t expect a meaningful balance right away.
- Nonforfeiture values: If you stop paying premiums, policies generally offer reduced paid-up coverage or extended term coverage instead of simply lapsing with nothing to show for it.
- Loan interest: Borrowing against cash value usually accrues interest, and unpaid loans reduce the death benefit.
Pro Tip: Ask your agent for an illustration showing projected cash-value growth year by year, along with the loan terms and interest rate, before you sign anything.
How long coverage lasts and what renewal really means
Term life typically comes in 10, 20, or 30-year lengths, and some insurers offer coverage to a specific age instead of a fixed term. Level term keeps your death benefit the same for the whole period, while decreasing term reduces the payout over time, a structure sometimes used for mortgage protection.
Renewability matters once your initial term ends. Many term policies are renewable annually after the level period expires, but premiums jump sharply because they’re recalculated based on your age at renewal rather than your original rate.
A few provisions determine how flexible your coverage is:
- Common term lengths: 10, 20, and 30-year terms cover most buyers’ needs, with coverage-to-age options for specific planning goals.
- Renewability: Annual renewal after the level term keeps you insured but at a steadily rising cost.
- Convertibility: A conversion rider lets you switch to permanent coverage within a set window without new medical underwriting, according to NAIC’s consumer guidance on term and cash-value policies.
- Limited-pay and single-premium whole life: Both guarantee lifetime coverage while changing how long or how much you pay upfront.
Which policy fits your situation
The right choice depends on what you’re protecting against and how long that need lasts, not on a blanket rule that favors one product over the other.
- Temporary income replacement: If your family depends on your paycheck, a term policy sized to replace several years of income is usually the simplest, most affordable fit.
- Mortgage protection: A term length matched to your remaining mortgage balance keeps your home covered without paying for insurance you won’t need once the loan is paid off.
- Young families on a tight budget: Term’s lower premiums let you buy a meaningful death benefit while money is tight, with the option to convert later as income grows.
- Lifetime dependent care: If you’re supporting a child with lifelong care needs, whole life’s permanence avoids the risk of outliving your coverage.
- Estate planning and liquidity: Whole life can provide cash to cover estate taxes or fund a special-needs trust without forcing heirs to sell assets.
- Cash-value savings goals: If you want a conservative, tax-deferred savings element bundled with insurance, participating whole life offers that combination, though at a higher cost than buying term and investing separately.
Your budget and your goals decide which path fits, not a universal formula. Someone with a new mortgage and young children has a very different answer than someone funding a trust for an adult child with a disability.
The “buy term and invest the difference” approach
The argument behind buying term and investing the difference is straightforward: term premiums cost a fraction of whole life premiums, so you put the savings into a retirement account or brokerage account instead, potentially coming out ahead over decades.
The strategy works only if you actually follow through. A few realities temper the pitch:
- Discipline matters: The savings only build if you consistently invest the premium difference instead of spending it.
- Investment returns aren’t guaranteed: Market-based accounts carry risk that a whole life policy’s guaranteed cash value doesn’t.
- Coverage gaps are a real risk: If your term policy lapses or expires before you’ve built sufficient savings, you lose your death benefit protection entirely.
- Some whole life designs aim to compete: Participating policies structured with paid-up additions try to accelerate early cash value growth, but they add complexity and cost compared with a plain term-and-invest approach.
If you’re considering this route, our Roth or Traditional IRA guide can help you figure out where that invested difference should actually go.
How to choose between term and whole life
A short set of questions can point you toward the right answer faster than reading every policy brochure available.
- How long do you need coverage? A fixed number of years points to term; a lifetime need points to whole life.
- What’s your monthly budget? If premiums have to stay low, term almost always wins on affordability.
- Do you want a savings or cash-value feature? If yes, whole life delivers it, at a cost; if no, term keeps things simple.
- Are you covering a specific debt or income gap? Mortgage balances and income-replacement windows map cleanly to term lengths.
- Do you have estate planning or special-needs funding goals? These often favor whole life’s permanence and liquidity.
Once you have a direction, take these concrete steps: calculate your coverage need based on income, debt, and dependents; get quotes from multiple insurers for comparison; request a full illustration if you’re considering whole life; confirm the insurer and agent are licensed through FINRA’s BrokerCheck; and ask directly about conversion options and surrender charges before signing.
Pro Tip: If you’re evaluating whole life, ask for a break-even timeline showing when cash value exceeds total premiums paid, plus the dividend assumptions used in the projection.
Our take on making this decision without the pressure
We think the biggest mistake isn’t picking term or whole life, it’s buying either one without comparing quotes or reading the illustration line by line. Sales pressure thrives on confusion, so take your time, run the numbers against your actual budget, and use our budgeting guides to see what premium amount truly fits.
— Win Personal Finance
Where to go next for budgeting and coverage planning
Deciding between term and whole life gets easier once you know exactly what room your budget has for a premium. Our personal finance advice hub walks through budgeting, saving, and income strategies that can help you figure out what you can comfortably commit to each month.
If you’re leaning toward buying term and investing the difference, our free financial wellness tools page can help you find a tracker to model that investment path, and a 50/30/20 budget calculator can show you exactly where a term premium fits into your monthly numbers. Start with your budget, then shop your quotes.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Is it better to have term life or whole life insurance?
Neither option is universally better. Term usually fits temporary needs and tighter budgets, while whole life suits people who want lifetime coverage or a cash-value feature, as NAIC’s buyer’s guide explains.
What does Warren Buffett say about whole life insurance?
We don’t have a sourced, direct statement from Warren Buffett specifically addressing whole life insurance to cite here. General investing commentary attributed to him favors low-cost index investing over complex financial products, but that’s a broader principle, not a specific verdict on life insurance.
Does Dave Ramsey recommend whole or term life insurance?
Dave Ramsey’s platform is widely known for favoring term life insurance paired with separate investing, though we don’t have a direct sourced statement to quote here. If that approach interests you, our breakdown of the buy term and invest the difference strategy above covers the trade-offs to weigh.
At what age should you stop paying term life insurance?
There’s no single age that applies to everyone; it depends on when your dependents are financially independent and your major debts, like a mortgage, are paid off. Many people time their term length to end once those obligations are gone, often in their later working years, but your own timeline should match your actual financial picture.
Does whole life insurance really build meaningful cash value early on?
Cash value typically grows slowly in the first several years of a whole life policy, and surrender charges can reduce what you’d receive if you cancel early. Ask for an illustration showing year-by-year projections, as AARP recommends, before assuming early cash value will be substantial.
Sources
- Life Insurance Buyer’s Guide
- Term vs. Whole Life Insurance and How to Choose
- Term Life vs. Whole Life Insurance: What’s The Difference? – Forbes Advisor
- Term Life vs. Whole Life Insurance: Which Is Better?